I’m hearing a lot from subscribers who are worried about rising rates. I get it. If you’re watching the financial news, it’s all they are talking about. And if you watch your portfolio (too?) closely, you see that the prices of your bond funds are declining.
Which, like, defeats the point of bonds. We’re here for the yield and not to give back our dividends via capital losses.
Bond prices fall as rates rise because, even if the bonds a fund owns are perfectly fine (paying their coupons on schedule), the value declines. Who wants to buy an old bond paying 3% if newer bonds pay more? In Bondland, investors are coin operated.
Municipal bonds are in the same bond boat.
Munis also trade inverse to interest rates and as rates rose, the value of previous-vintage muni bonds declined.
The question is: Do we stick to our munis, holding through thick and thin, or instead, should we sell our muni funds to sit out this “rate drama” and head back into them when rates calm down?
You know well that I like data. Cold, hard numbers. So, I created a spiffy new rate-timing indicator:
- When rates rise and look like they’re about to run away, we sell our muni funds and sit in cash.
- We then wait for an “all-clear signal.” Something that says rates are calming down. Then, we head back into our muni funds.
Sounds pretty good, right? I know, I was proud of it when I concocted it. A better way to buy munis!
But unfortunately, I found that it’s not! It costs you money because, while it certainly worked great during the bond firestorm of ’22, the “signal” fires way too often to be useful. Its cardinal sin is that it misses the rebounds.
Here’s what $10,000 invested in both strategies—buy and hold on the one hand and rate-timing signal on the other—looks like over 18 years:
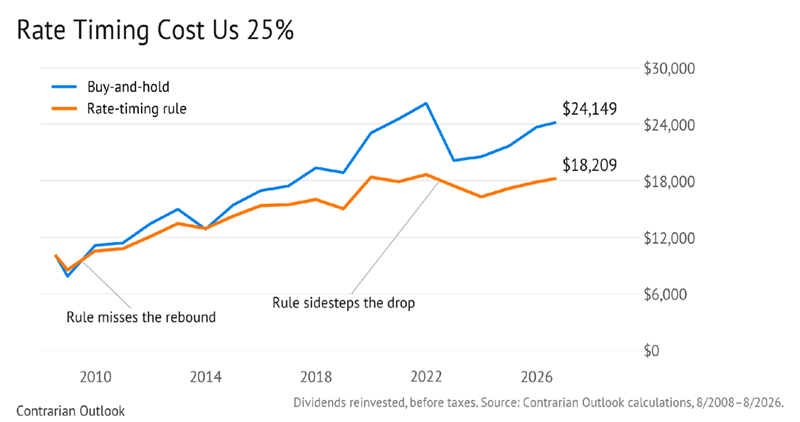
If you bought and held your $10,000 investment in muni funds in 2008, it grew to $24,149, including dividends. Rate timers using my model only ended up with $18,209! Moving in and out cost them about 1.6 percentage points a year in returns. And that compounds year over year, leaving you with a whopping 25% less.
What a cost! Buying and selling left less principal to generate tax-advantaged income. Yes, it sounds smart but rate timing in reality doesn’t work.
This, by the way, is a common mistake vanilla investors make all the time. They sell at the lows and they’re late returning to the party. They must be right twice: when to sell and when to buy again. And it’s extremely rare to be right once, let alone both times!
A heads-up that this study only includes funds that are still active today. Two national muni funds were merged out during the window. This could bias the results toward buy-and-hold a bit.
Here’s another strategy that works. Let’s say you don’t yet own any munis. When to buy? When they’re cheap versus their own history. I ran the numbers on this one, too.
I took a mix of three different muni groups. At the end of each month, from 1999 to the end of 2025, I put the funds into three valuation buckets: cheap, fair, rich.
Cheap means the fund’s discount at that month-end was well wider than its own average over the prior year (or its premium well smaller). Rich means the opposite, and fair meant it was trading in between.
For our muni groups, our pricey funds trailed their cheap counterparts by 0.7% to 0.9% per year. The better entry strategy was to buy the bargains and hold ‘em.
So, if you’re holding munis today, don’t fold ‘em—as long as the payouts hold! History says the prescient play will be patience.
In this sample, it paid nearly a full point a year to buy bargains in muni CEFs. And because we know how much that compounds, well, it pays to stay patient.
The other nice thing about these bond funds: They pay monthly dividends. On Friday, in my next issue of Contrarian Income Report, I’ll discuss the best bond funds to buy to take advantage of the current rate scare. Unfortunately, since you’re reading this, I don’t have you down as a current Contrarian Income Report subscriber. But we can easily remedy that. Click here and I’ll set you up with a risk-free trial and my research on current monthly dividend payers yielding 11%+.