Three investors walk into a bar and start talking retirement. But just two of them volunteer their honest opinions.
The third sits there and haughtily judges them!
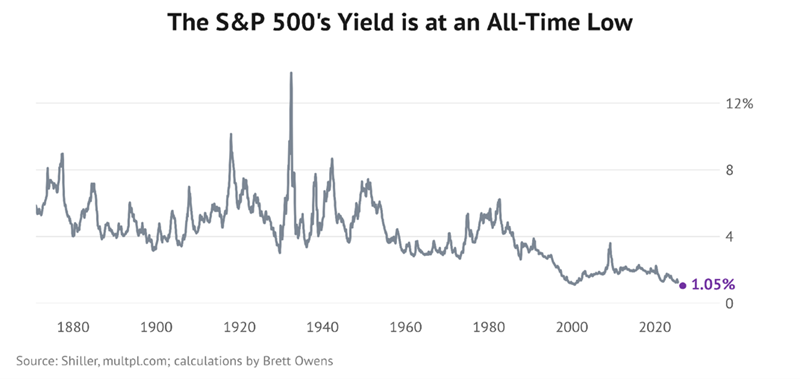
First up, a 75-year-old retiree. He looks at what the S&P 500 (America’s ticker!) offers these days. Today, it’s never paid less. Our veteran investor shrugs and gives up on dividends: “Not much you can do about these paltry yields.”
His counterpart is a 79-year-old who was told as a young man that he would care more about his dividends as he aged. Yup. (Spoiler alert! “They” were right, the man says. More from him later.)
Meanwhile, their judgy counterpart is, of course, a professor! He lacks their experience in the markets but that doesn’t stop him from casting aspersions. They’re both kidding themselves, he taunts. He even has a name for their mistake: the “free dividend fallacy!”
One correction on the story above. It wasn’t a bar—all three turned up in the same Wall Street Journal story. Yet reading it made me feel like I’d been overserved at our hypothetical dividend tavern. Let’s break down why the investors’ stories are relevant to our retirement goals.
First, the 75-year-old shrugging about low yields. Why? I suspect two reasons.
For starters, his quote smells like a roll of Benjamins. The type rich guys peel off and give to their kids. In fact, he mentions in the story that rather than reinvest his dividends, he’s handing the checks to his children instead.
Obviously not a dude who needs every dividend payment. He’s a retired doctor, and I assume his cash pile climbs plenty high.
But lots of dough, believe it or not, can be an income handicap. You receive too much vanilla financial advice. He mentions money market funds and yes, when your nest egg is sizeable enough, 3% payouts will cover the bills. And you can lament it is what it is at the country club without too much actual pain.
For you and me though, the multi-million-dollar option isn’t on the table. And that’s OK because we have available lanes on our income highway that pay 7%, 8% or even better. This yield advantage lets us generate as much passive cash flow on our $1 million as our doctor friend does on $2.5 or $3 million.
With 8% yields, we can collect $80,000 on a $1 million nest egg, without having to sell a single share. That’s 7%, or $70,000, better than America’s ticker, which yields an all-time low 1% today:
And here’s the advantage of this strategy: It makes our day-to-day way more peaceful and a lot less stressful. We don’t have to follow the market. We don’t live by whether the S&P 500 is up or down today. Yes, our account balance bounces around with everyone else’s. Our income doesn’t.
Here’s why. That $80,000 works out to $6,667 per month, hitting our account like clockwork. Now, contrast that with the withdrawal strategy—selling shares every month to raise the same $6,667. Suddenly, it matters a great deal whether the market is up or down!
A down market becomes the worst thing for us, because we must sell more shares of SPY to raise our $6,667. We find ourselves rooting for the market to rally so we sell fewer. But the market doesn’t care what we need! The market does what the market does and this market is a roller coaster. Do you want a bad month putting a dent in your retirement?
Here’s the choice. I ran the numbers on it. You can take $1 million in SPY and withdraw $6,667 every month, selling shares along the way. But if you try this during a down year like 2022, you’ll consume 36% more of your shares than selling in a calm year. And the shares are gone for good!
See, the problem is that when we sell lots of shares low, these shares never come back. Our principal has been reduced—permanently.
Our professor friend says it’s all the same. Well—how is it all the same if we sell more shares when stocks are low?
To be fair, the professor has a point. Dividends are not free money. When a company pays out a dollar, the share price drops by that dollar. He’s right about that.
He’s also right to warn people who chase a yield without verifying the income stream behind it. Market history is filled with companies that paid dividends they couldn’t afford to keep investors from selling, only to hit the wall and lose them with a dividend cut later.
We, as careful contrarians, know this. We do the math on what’s funding our dividends before we buy them. We check that a fund earns more than it pays out. When it does, the payout comes from profits—not from our principal. The fallacy only bites the folks who never check.
Where the professor loses me is at diversification. He warns that dividend investors end up un-diversified. That’s true, if you don’t know what you’re doing. Our income portfolio spreads across six independent buckets, among them Safe Muni Bonds paying 7% to 8% (federal tax-free, so we keep more of it), Energy Toll Collectors—our oil and gas pipelines—and our Dividend Lifeboats, covered-call funds paying 9% to 11%. Plus, a bond-fund lane paying up to 17% (yes, 17%). And two more buckets we’ll save for another day.
These six payout streams don’t rely on the same engine. For example, muni coupons don’t care what option premiums did this month.
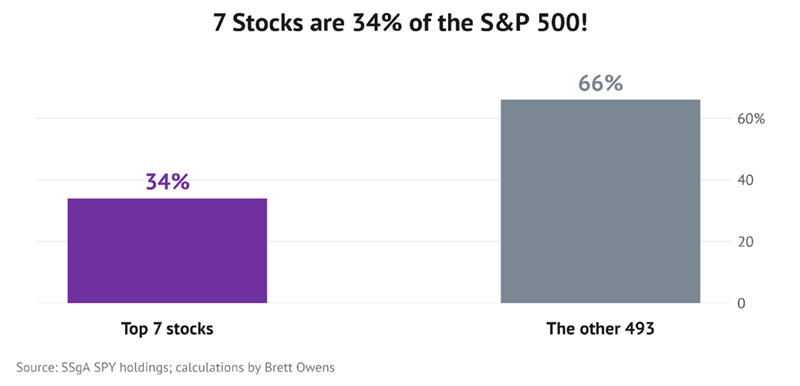
Contrast that with the S&P 500. Did you know that just seven stocks make up one-third of the index? One-third! Should be called the S&P 7:
And here’s the uncomfortable part that newbie dividend investors don’t want to hear: Dividends can disappear. UWM Holdings (UWMC) suspended its dividend and its stock plunged 35%. Papa John’s (PZZA) pulled its payout the very next day.
When we build an income portfolio, we’re not buying, holding and closing our eyes forever. We watch our payers. We make sure the businesses we own keep generating enough cash to fund their payouts. If and when the landscape or the fundamentals change, we move money between positions.
In other words, we never have to sell shares to pay the bills. When we move money between payers, that’s our choice—made on our schedule.
And hey, if we’re doing it wrong according to a judgy WSJ professor, that’s just fine with us.
Which brings me back to our 79-year-old friend at the bar. As a young man he was told he’d care more about his dividends with every year that passed. Now comfortably retired, he says, “Now I can attest to that as fact!” Smart… and our kind of guy! The professor can keep the fallacy. We’ll keep the checks.
And if you like the idea of 8% dividends, how about twelve percent? This life-changing 12% dividend is about to drop its next payout—click here for the details.