One day in the not-too-distant future, everything will change.
You’ll be telling your children or grandchildren about it – how that was the moment that money transformed.
I’m not talking about dollars becoming digital and moving across blockchains… or how stablecoins are now a direct form of government debt.
That’s already happened.
What I’m alluding to is something much more fundamental.
The very mental construct of money.
Money will no longer be the dollars in your checking account or the billfold in your pocket.
Our understanding of money will become much broader. That’s because everything and anything of value will be more than just an “asset.” It will be money.
We’ve been slowly unpacking this idea over the last few issues. We started with the U.S. Treasury laying the groundwork for an onchain financial system to thrive.
It’s been preparing to allow stablecoins to grow at an accelerated pace with the stablecoin GENIUS Act soon to go into full effect in January…
Today we’re getting into the other side of that equation. The assets themselves.
The Tokenization Event
Tokenized stocks issued by Coinbase went live natively on Base this week. Coinbase has tossed its hat in the ring with participants like xStocks, Ondo Finance, trade.xyz, Robinhood, Securitize, and others.
But looking at Coinbase’s project specifically…
Base is a layer-two chain on Ethereum. That means Base gains Ethereum’s security properties and network effects while prioritizing the chain for lower transaction costs and higher speeds.
It started with a list of the usual suspects… Nvidia, Apple, Meta, and Alphabet.
The tokens are backed 1-to-1 by real shares, which are held by the regulated broker and custodian Alpaca. The token is then issued by a Coinbase entity that sits in Abu Dhabi Global Market.
This legal setup ensures that token holders have a legal claim on the shares. An important technical detail has to do with the token itself. It uses what’s called a “B20 standard.”
If you’re familiar with token standards, you’ve probably heard of “ERC-20.” You can think of it as the “operating system” for most digital assets in the Ethereum ecosystem. This includes tokens such as LINK, UNI, or AAVE. Even stablecoins such as USDC and USDT are primarily ERC-20 tokens.
B20 extends the ERC-20 standard. This means the token works with existing wallets and various protocols. This is important to consider as many protocols in decentralized finance (DeFi) work seamlessly with this standard.
The reason Base created this standard was to more easily handle dividends and stock splits. This way, during corporate actions, B20 tokens don’t suddenly break DeFi solutions.
Without it, a stock split would split one token into five and could suddenly liquidate a loan. The B20 standard addresses this concern.
What’s exciting about these tokenized stocks is the lack of a whitelist. Many believed tokenized stocks on public blockchains would require various permissions to gate or grant access to certain people.
But the system functions without this filtering mechanism. It truly becomes a permissionless ecosystem.
In fact, about 50 third-party protocols expressed support for the token standard. This includes names that should be familiar to Permissionless Investor readers, like Morpho, Euler, Aave, and Aerodrome, among others.
This is our tokenization thesis playing out in real time. The future of finance will reside on permissionless protocols and public blockchains. Innovation is about to accelerate. And these networks are about to realize a type of demand never seen to date.
And when we pair this trend with autonomous machines, it becomes even more powerful.
But the consequences are not well understood…
The Endgame
The Jackson Hole Symposium is happening over the next few days. It’s where central bankers and policymakers gather to discuss the financial system.
They typically discuss topical research along with major trends seen across the globe. One of my favorite things to do each year is look through the research papers submitted alongside the presentations. For an outsider looking in, it’s our best peek into the minds of central bankers.
This year’s topic is noteworthy. That’s because cryptocurrencies and stablecoins are on the docket.
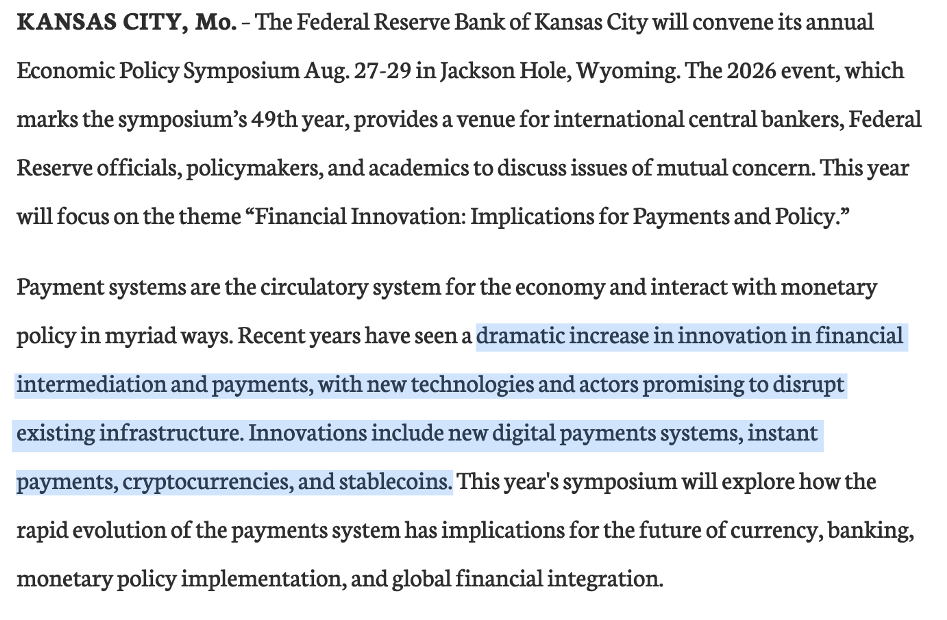
Source: kansascityfed.org
I’ve been waiting to see this for many years. And the timing is no coincidence.
The U.S. Treasury is already pushing ahead with its plan to leverage stablecoins to make the dollar more flexible and to protect its reserve asset status.
Fiat currencies moving across permissionless rails in the form of stablecoins is one thing. But what happens when the same thing comes for stocks? What happens when sending one share of Nvidia (NVDA) to somebody becomes as easy as transferring money on a payment app?
Would you accept payment in the form of a highly liquid, stock-backed token? Could you, one day, pay for your groceries, gas, or even your mortgage with shares of Apple, Nvidia, or Tesla?
It’s not as crazy as it sounds. And it’s a discussion that needs to be had.
Most scholars focus on horror stories, mostly around central bank digital currencies (CBDCs). The specter of “use-it-or-lose-it” money, freezing accounts, or surveillance measures also gets a lot of attention.
What I don’t see discussed is what happens when people no longer need dollars at all. At least not for everyday purchases. That could be an endgame that bolsters the economy best equipped to disseminate financial assets.
The world is about to become inundated with U.S. dollar stablecoins to help facilitate the financial plumbing onchain. But what happens when those same dollar holders move into the very assets moving onchain?
Those assets represent a life raft as public blockchains become flooded with stablecoin liquidity.
This is not an event that will happen overnight. But this looks to be the trajectory – a future that is truly frictionless and interoperable.
How Gold Could Become an Income Machine For You [sponsor]
Just one click and you could start collecting extra monthly income up to $1,152 per month like clockwork from gold.
Click here to discover the $15 fund delivering serious returns.