This company handed nearly one-third of its value back to shareholders last year. I’m talking about 30.5% of the market cap back to its owners!
By contrast, the S&P 500 yields 1.0%, an all-time low. So we’re talking about a stock that is dishing 30 times the dividend yield of “America’s ticker.”
The headline yield on Albertsons Cos. (ACI) doesn’t do its “total yield” justice. It reads 5.5%. Sure, but the grocer also offered an additional 25% rebate via buybacks. This number is invisible to every yield screen, stock scanner, and (yes) AI prompt asking about dividends. Which is great for contrarians like us searching for value!
ACI isn’t alone. Below we’ll talk about five total yield monsters (ACI included) that are buying back their own dividend-paying shares like crazy. This is a wonderful 1-2 punch because each repurchased share increases the value of each remaining share. And it makes sure that the next dividend hike packs even more power because that can (and often does!) ignite a flagging share price.
It’s a phenomenon I call the “Dividend Magnet.”
The logic is simple. Investors are attracted to companies that fork over more and more cash to pay bigger dividends each year. It’s not just the income, either—each dividend-increase announcement is a loud signal that business is so good, and they’re making so much cash, that they can afford to pledge even more money for its stockholders.
Let’s take a look at those five potential Dividend Magnets in the making that are paying us from 7.2% to 30.5% in “all-in” shareholder yields.
United Parcel Service (UPS)
Dividend Yield: 6.1%
Total Yield: 7.2%
United Parcel Service (UPS) gets just about anything one can think of from Point A to Point B—express letters, documents, packages, even freight—across more than 220 countries. It also provides a number of other services, including international air and ocean freight forwarding, customs brokerage, healthcare logistics and much more.
At first glance, UPS looks like a steal. We’re able to earn more than 5% from one of the world’s largest courier companies and a true blue-chip stock? And we’re getting a couple additional points from buybacks?
What’s the catch?
UPS Is Spending a Lot but Going Nowhere Fast
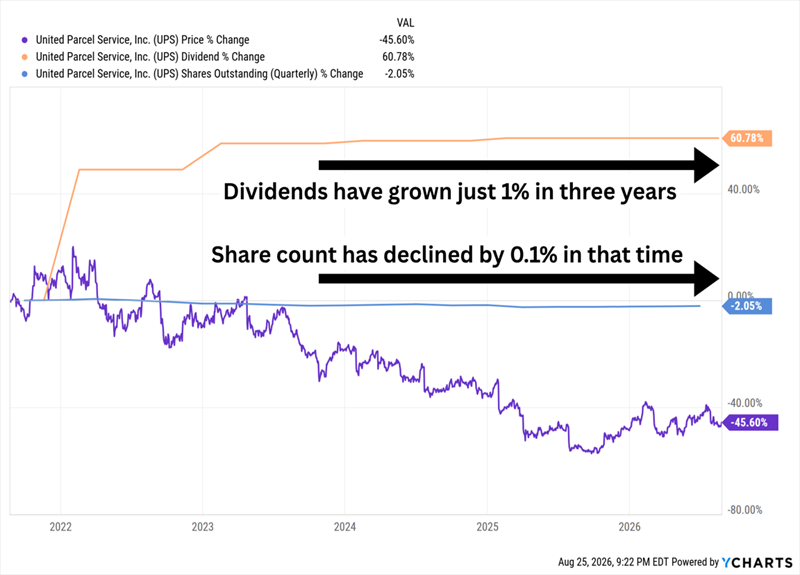
UPS shares have hemorrhaged thanks to pressure on several fronts. It has been cutting out low-margin shipments from its largest customer, Amazon (AMZN), while trying to pivot toward more lucrative services. Spiking oil prices haven’t helped, nor have shrinking shipping volumes.
United Parcel Service has been trying to throw shareholders a lifeline by throwing billions of dollars in cash at dividends and buybacks, which is laudable.
But the math is uncomfortable. Dividends are eating up 90% of 2026 adjusted earnings estimates and virtually all of the company’s free cash flow—leaving almost nothing in reserve if business deteriorates further.
CFO Brian Dykes has already said the dividend won’t be raised this year. But that might be a best-case scenario.
H&R Block (HRB)
Dividend Yield: 3.2%
Total Yield: 9.7%
H&R Block (HRB) is a tax-preparation company that provides both assisted and do-it-yourself prep solutions not just in the U.S., but also Canada and Australia. It has other businesses, including small business financial solutions, term loans and tax identity protection, but tax prep is the bedrock here.
It’s a fairly cyclical business insofar as a larger employment base provides H&R Block with more customers. However, one thing that remains the same from one year to the next is the complexity of tax codes, creating constant demand for its services. The company has delivered four consecutive years of stable if not growing revenues and profits (and is expected to deliver a fifth in 2026), but prior to that, HRB went through plenty of wavering on both the top and bottom lines.
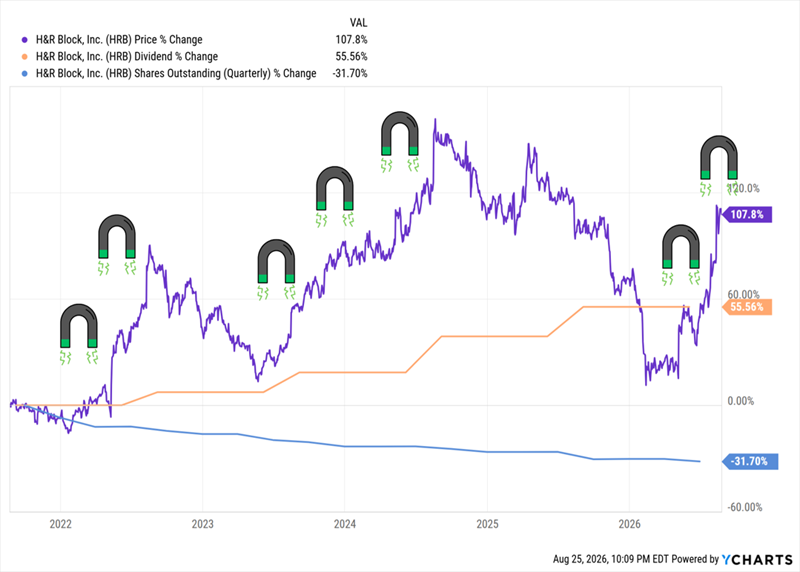
H&R Block has been plenty steady with shareholder rewards, however. The dividend has grown for 12 consecutive years and has either been stable or rising for almost three decades. Buybacks rarely will be as consistent as dividends, and that’s the case with HRB. Still, share repurchases have been part of the cash gameplan for years, and its recent heavy buying takes a modest 3% dividend yield to a shareholder yield of almost 10%.
While HRB shares have been volatile over the past few years, dividends and buybacks have helped lift the stock over the long run.
That Cash Makes a Difference
The stock doesn’t trade for as deep a discount as it did a few months back, but HRB still looks cheap. It’s priced at less than 9 times 2026 earnings estimates and a price/earnings-to-growth (PEG) ratio of just 0.7. (Remember: A PEG of under 1 is considered undervalued.)
Preferred Bank (PFBC)
Dividend Yield: 3.1%
Total Yield: 10.7%
Preferred Bank (PFBC) is a California-based “regional” bank that provides a wide variety of banking products and services. That includes a number of personal offerings such as checking, savings and money market deposit accounts. And it also includes things like commercial loans, real estate mortgage loans, term loans, SBA loans, trade finance and more.
Why “regional”? Preferred’s Los Angeles headquarters and 11 full-service branches in California make up the majority of its physical footprint, but not all of it—PFBC also has a branch in Flushing, New York, and another in the Houston suburb of Sugar Land. Also of note: The company was originally founded as a Chinese-American bank; while most of its business is more mainstream nowadays, Preferred says it still continues “to benefit from the significant migration to California of ethnic Chinese from China and other areas of East Asia.”
PFBC is a longtime growth story backed by generally high-quality assets. It ran into top- and bottom-line hurdles in 2024 and 2025, but the company at least appears to be getting back on track. Deposits and loans are inching higher again, and margins are improving.
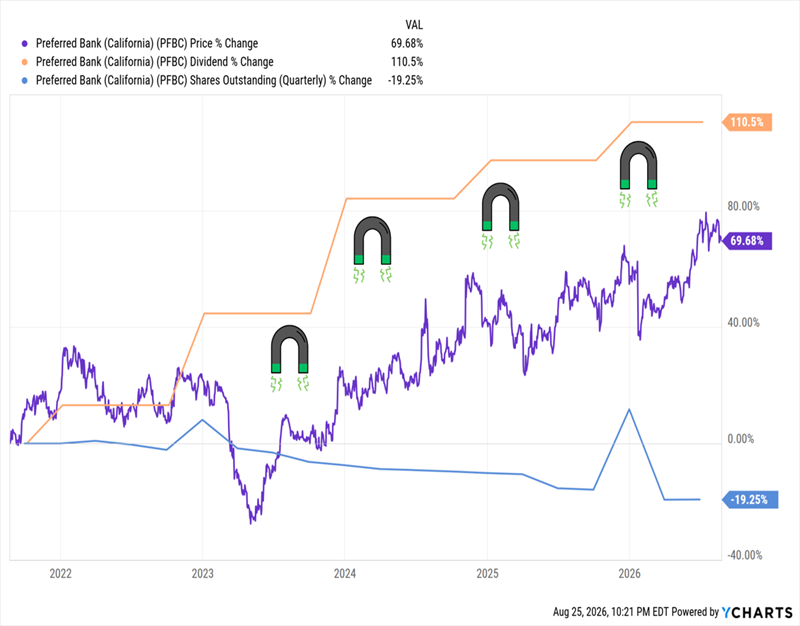
Investors powered through that two-year operational slump, choosing to keep their eye on the growing amount of cash Preferred Bank has been dishing out. The company has more than doubled its dividend over the past five years, and it shelled out an all-time high $93 million in share buybacks in 2025.
The Dividend Magnet Kicked On When PFBC Ramped Up Repurchases
Preferred Bank isn’t particularly cheap, though. Its sub-10 forward P/E, while nominally low, is on the high side compared to the past few years. And while PFBC historically trades at a premium to book, its 1.6 P/B is relatively high, too.
Oxford Industries (OXM)
Dividend Yield: 7.6%
Total Yield: 18.1%
Oxford Industries (OXM) is a “lifestyle” apparel company. Brands like Tommy Bahama, Lilly Pulitzer, Southern Tide, Duck Head and others sell a variety of clothing and accessories. But they also offer (or license their brand names to others who sell) indoor and outdoor furniture, bedding and bath products, fragrances, even resort operations.
It’s rare to find dividends this rich in any consumer company, let alone a high-end cyclical name. We can thank both aggressive dividend growth and a hemorrhaging of shares over the past few years.
A Fat Dividend and Buybacks Haven’t Been Enough to Pull Shares Higher
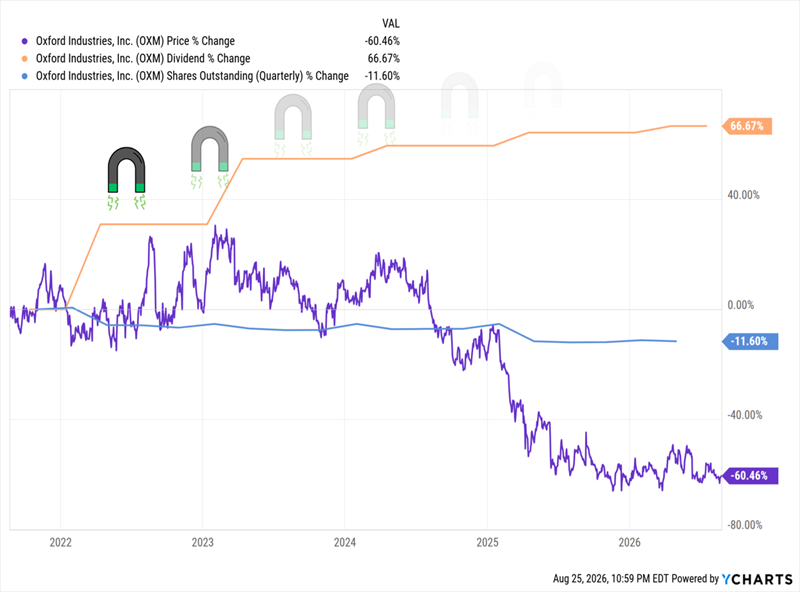
Given its brands’ wider offerings and an affluent target consumer, Oxford’s financials have historically been less fickle than the average mall retailer. But the company ran into trouble in 2023 when it had to write down $114 million, most of which was impairment charges for the Johnny Was business it acquired in 2022.
But investors have really been spooked over the past two years. Revenues retreated in both 2024 and 2025. While profits still rebounded in 2024, the company actually absorbed a net loss last year thanks in large part to another impairment charge connected to Johnny Was.
OXM’s bottom line is expected to snap back hard; adjusted earnings estimates are for a mid-teen improvement this year and a 20%-plus jump in 2027. Dividend investors should hope so. While the company has continued to grow its dividend despite financial turbulence, its projected $2.80 in annual dividends will far outstrip the $2.46 it is expected to earn this year, and it would be tightly covered under next year’s projected $3.02.
Oxford has ratcheted back repurchases, so it’s possible it’s defending its dividend. But investors should know that OXM has played fast and loose with its distribution, cutting it both during the pandemic and Great Recession.
Albertsons Cos. (ACI)
Dividend Yield: 5.5%
Total Yield: 30.5%
Albertsons Cos. (ACI) is one of the largest grocery and pharmacy chains in the country, boasting 2,240 retail locations under brands including Albertsons, Safeway, Vons, Jewel-Osco, ACME, Shaw’s, Star Market and many more.
Consumer staples stocks typically deliver above-average income, but Albertsons is in a class of its own: a 5%-plus yield at current prices, and that’s before we count ACI’s show-stopping buybacks.
Albertsons previously had a history of buying back a few shares every year. But the company’s planned merger with Kroger fell apart in late 2024, and in 2025, it pushed forward with a $750 million accelerated share repurchase (ASR) and increased its existing authorization from $2 billion to $2.75 billion to accommodate the ASR. All told, the grocer ended up spending roughly $1.5 billion on repurchasing nearly 79 million shares. The company then tacked on another $900 million to its authorization in April 2026.
ACI also announced a 13% increase to the dividend in April, to 17 cents per share.
That $1.5 billion spent on buybacks plus $323 million worth of dividends is how a $5.98 billion company delivers a 30% shareholder yield.
But That Still Hasn’t Been Enough to Keep the Dividend Magnet On
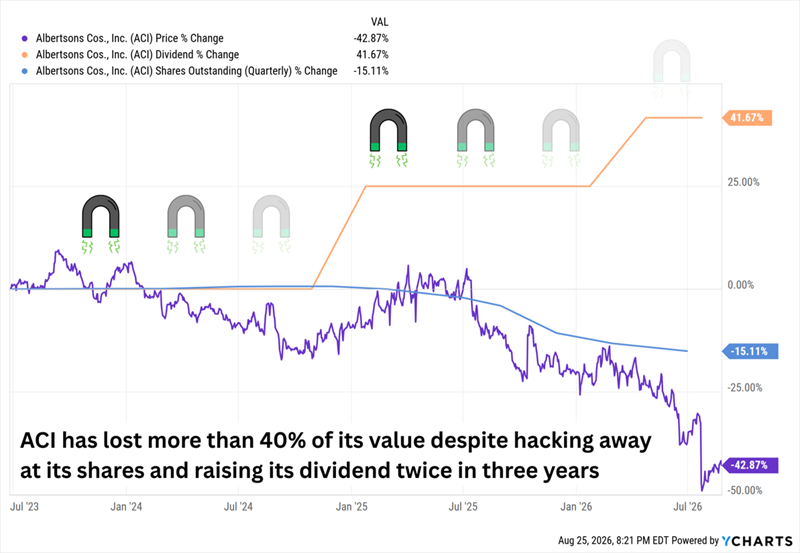
Albertsons has given shareholders very little to crow about. ACI is coming off a lousy Q1 in which earnings missed and the company cut its full-year earnings guidance by about 20%. The Inflation Reduction Act has weighed on the company’s pharmaceutical operations. CEO Susan Morris warned about “a more cautious consumer.” The company’s president and CFO, Sharon McCollam, announced she’ll retire later this year.
The bull case? ACI’s yield has plumped up (and remains extremely well-covered) while its forward P/E has been whittled down from nearly 11 last spring to below 7 today. But Albertsons still needs a catalyst, whether that’s its recently announced “ACI Edge” restructuring bearing fruit, or a strengthening in consumer sentiment.
5 Dividend Magnets Poised to Double in 5 Years or Less
ACI and a couple of these other tickers are going onto my watch list. They’re interesting “Magnet” candidates. They’re just not ready for primetime … yet.
But these five Dividend Magnets are.
I’ve just put out a new, in-depth report on five must-own companies that are poised to double their share price and triple their dividends … within the next five years!
Each of these stocks are producing the dividend growth and the buybacks we need for liftoff, as well as a third indicator that shows they’ll help protect our wealth, too.
Personally, I think rapid triple-digit gains are squarely on the table with these 5 hidden gems. But conservative sort that I am, I’m forecasting steady 15%+ potential annualized returns for the long haul.
These five picks include …
- A tech-savvy insurer with nearly 200% dividend growth over the past decade
- An “AI backdoor” Dividend Magnet
- A serial raiser that has nearly quintupled its dividend since 2016
There’s still time to get in, and I want to make sure you do.
Click here to learn about these five “Dividend Magnets” that are set to double, as well as an exclusive briefing on my Hidden Yields system. It reveals more on these dividend growers I’m pounding the table on now, as well as an explainer on how Hidden Yields works, and an offer to try the service out 100% risk-free for the next 60 days.