Here’s something we never hear about: The wonderful things that can happen when a stock “pays us back” in dividends.
It’s a shame more dividend investors don’t consider this, because it really is the “holy grail” for us contrarian income players!
What do I mean by “pays us back”? One way to think about dividends is as a small slice of corporate cash flows handed over to us as cash. Eventually, that cash will exceed, on a per-share basis, the amount we paid for the stock in the first place.
Once that happens, everything else is, well, gravy.
I bring this up now because one of our long-time Contrarian Income Report holdings is about to hit this mark. Others are hot on its tail.
Below, we’ll talk about this fund, which yields 12.2% today and pays dividends monthly. We’ll also discuss a business development company (BDC) we’ve held for just under five years. Since then, the stock has handed us nearly half of our original buy price in payouts.
Our buy windows on both of these tickers are still open. The sooner you pick them up (or add to an existing position), the faster your dividends will pile up!
This “Bond God” Favorite Covers 97.6% of Our Purchase Price
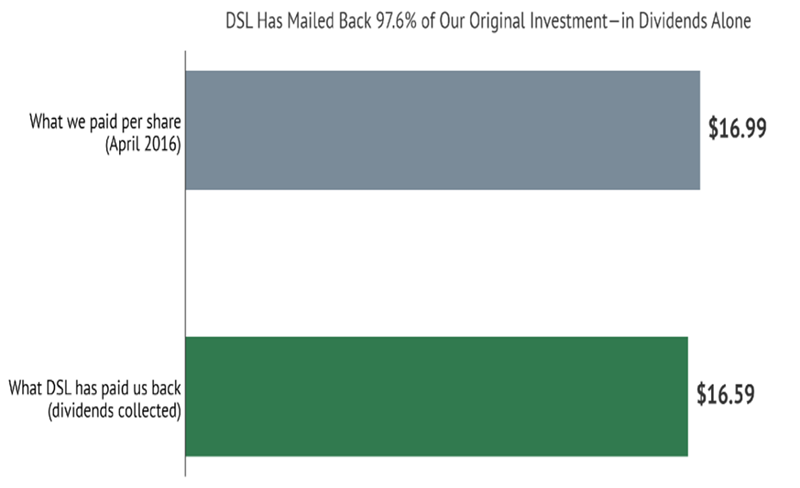
We bought the DoubleLine Income Solutions Fund (DSL) in April 2016, less than a year after we launched Contrarian Income Report. At the time, it traded at $16.99 a share. Just over 10 years later, we’ve collected $16.59 a share in payouts, or 97.6% of our original buy.
Since DSL pays dividends monthly, four months from now, we’ll be fully “comped”!
Source: Contrarian Income Report
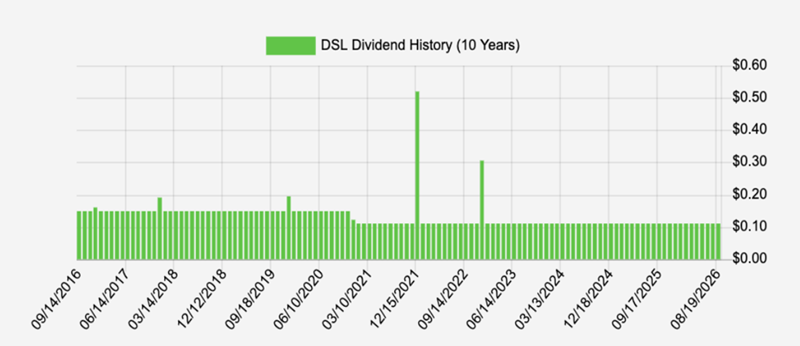
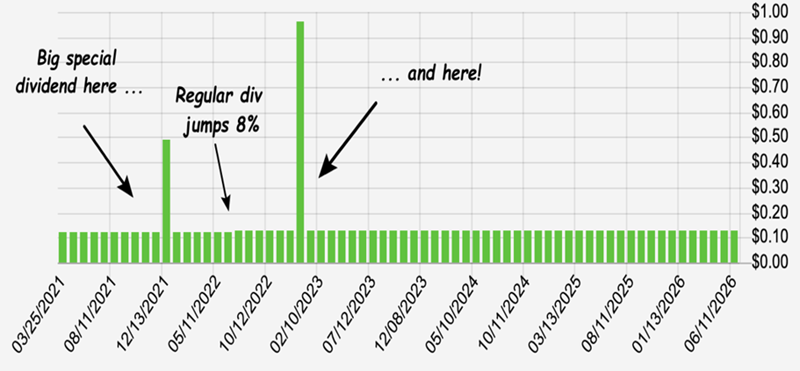
In that span, DSL’s dividend has only moved lower once, in the pandemic-rattled market of 2021. That was smart risk management. And since then, the fund, run by the “Bond God,” Jeffrey Gundlach has kept the divvies flowing, with two healthy special payouts thrown in:
Source: Income Calendar
Fast-forward to today, and DSL is our only remaining holding from those relatively blissful pre-COVID days.
The fund has also posted a 92% total return (with dividends reinvested) since our original buy. That’s far ahead of the go-to index fund for high-yield bonds, the State Street SPDR Bloomberg High-Yield Bond ETF (JNK).
DSL Leads the Bond Pack (Thanks to Its Dividend)
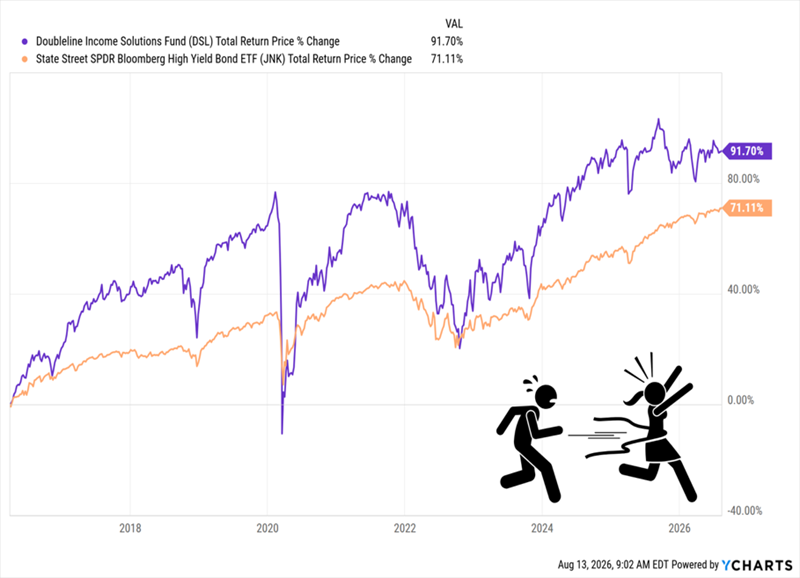
That’s a big move for a bond fund at any time, and especially during a particularly wild time for bonds. It included periods of essentially negative interest rates (during the pandemic) and times of skyrocketing inflation (2022, when the CPI hit 8% and the Fed pushed rates from essentially zero to north of 5%).
Soaring rates are, of course, bad for bonds (rates up, bonds down).
Where does that leave us? Despite Fed Chair Kevin Warsh’s jawboning on higher rates, I still expect lower rates in the longer run as AI use spreads, cutting companies’ costs (including, yes, on hiring) and curbing wage growth.
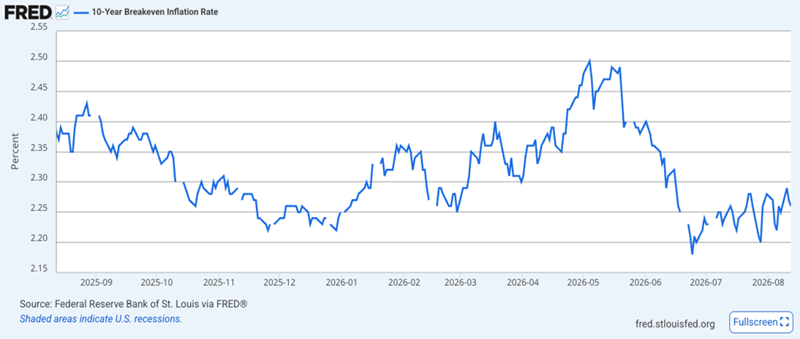
The bond market agrees—something our suddenly tough-talking Fed chair no doubt knows. Its 10-year breakeven inflation rate (a forecast of where the market sees inflation heading) has been on a steady slide and is hovering around 2.25%. That’s “close enough” to the Fed’s 2% goal.
Lower rates also cut DSL’s borrowing cost. That matters for a fund with 23.5% leverage—a “Goldilocks” level that boosts returns without taking on too much risk if rates suddenly rise.
But look, we don’t pretend to know the future. We’re simply playing the odds. Sometimes the market zigs when we were expecting a zag. And with bonds, the main risk is duration, and being locked into yesterday’s lower-paying issues as rates rise and new, higher-paying bonds are issued.
As I write this, DSL holds about 53% of its portfolio in bonds with durations of 0 to three years, with a further 23.1% at three to five years. That’s a nice balance, letting Gundlach & Co. lock in decent yields while maintaining flexibility.
And since DSL is a closed-end fund (CEF), we can further protect ourselves by demanding a discount. And man, is the Bond God giving us one.
DSL’s Overdone Discount
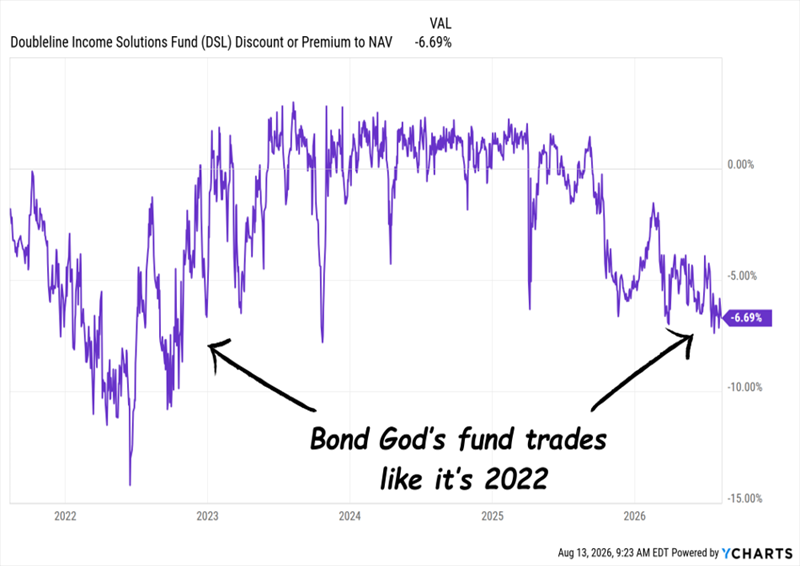
As I write, DSL trades at a discount to net asset value (NAV, or the value of its underlying portfolio) of 6.7%. That’s below the fund’s five-year average discount of 2.4% and near levels not seen in any sustained way since the end of 2022—annus horribilis for bonds.
That’s more than enough compensation for the minimal duration risk we’re taking on, especially with Gundlach at the helm. We’ll happily take the discount and start (or add to!) our pile of dividends from this exceptional 12.2%-payer.
Ares Is Almost Halfway to “Paying Us Back.” Here’s How It Gets There
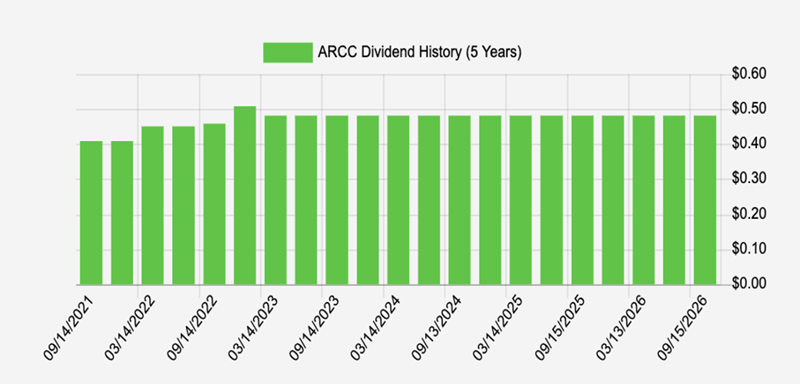
Ares Capital (ARCC) is our “BDC bully”—the biggest in the business. It’s also a bully on the dividend front: Since we bought almost five years ago, in September 2021, Ares has handed us $9.41 a share in total dividends, nearly halfway to “comping” our $20.36 purchase price. And if you’d reinvested your payouts, you’d have done just fine, too, with a 57% total return.
If you run a small business, you know it’s a hassle to get a loan from a bank. Enter BDCs, which loan cash to these firms and pass the interest to us as dividends. And its dividend—current yield: 9.5%—is rich, in part because BDCs (much like REITs) must pay at least 90% of their taxable income as dividends by law.
Over our holding period, it’s raised its regular payout twice and delivered a modest special dividend (the longer line in late 2022 below), too:
Source: Income Calendar
It is true that 71% of ARCC’s portfolio is floating-rate, and that’s been a plus as rates have risen and stayed relatively high.
This floating-rate concentration does pose risk as rates fall, but management is doing a nice job of offsetting that risk by originating more loans: At the end of the second quarter, it had loans out to 619 companies, up sharply from 566 a year ago.
And because Ares is the biggest player, it can be picky, only lending to the most creditworthy borrowers.
You can see that in the quality of its loan book: In the second quarter, 59% of ARCC’s loans were of the first lien senior-secured variety. That means it’s first in line to be repaid if any of its borrowers run into difficulty.
And even if rates do come down from here, as we discussed earlier, it’s likely to be a gradual decrease, giving ARCC ample time to adjust.
Finally, there’s AI, which small- and medium-sized businesses are embracing: According to Goldman Sachs (GS), 76% of small businesses are using AI in the US, with 93% of those users saying it’s had a positive impact.
As AI saves costs and boosts business for smaller companies, they’ll grow—and Ares will be ready to supply the loans they’ll need. We’re here for it, too—happy to collect the stock’s 9.5%-yielding payout on our way to a full “dividend payback” on our shares.
My Favorite Bond Fund Puts Us in the Fast Lane to “Dividend Repayment”
This “dividend repayment” clarifies our strategy pretty well.
We want to recover our upfront investment in payouts, and we want to do it as fast as possible.
Yes, we want the highest yields we can get. But we will never compromise on safety. Plus we want monthly payouts so we can reinvest our payouts faster. Or, if we’re using them to fund our lifestyles, get them to roll in monthly, so they’re dropping into our accounts as our bills come out.
To that end, I’m pounding the table on another high-yielding bond fund that’s also screaming bargain now. Check out this pretty payout picture:
That 12% payout checks all our boxes:
- It’s high, paying us 12% now.
- It’s paid monthly.
- It’s managed by another top-flight manager, who’s been recognized by his peers for his consistently strong performance.
Best of all, this fund is cheap, positioning it to gain when rates move lower. And if that takes a while to happen, that’s fine—we’ll happily get paid 12% a year while we wait. (That’s enough to “repay” our upfront investment in a little over 8 years—faster than DSL’s trajectory.)
The faster you buy this 12% payer, the sooner you can start piling up your payouts—and getting on the road to collecting your upfront investment in dividends alone. Click here and I’ll tell you more about this unique fund and give you a free Special Report revealing its name and ticker.