Look, we contrarians always welcome a market rally like this one. But it does make our hunt for yield harder.
I mean, the S&P 500’s surge has ground down the index’s average yield to levels not seen since the 1800s!
Right now, the go-to index fund, the State Street SPDR S&P 500 ETF Trust (SPY) yields 0.98%. So you’d be pulling in a pathetic $9,800 on a million bucks invested. To get a liveable $50k in income, you’d need to invest $5 million.
Yikes!
Clearly, we need to widen our “strike zone,” and look beyond dividend yield to get the dividend cash we demand. So we’re looking to another kind of yield: shareholder yield.
Shareholder what?
Shareholder yield is a complete measure of how a stock rewards us, accounting not only for dividends but share buybacks, too.
Even better if a company is growing its dividend. That way, we get my favorite “trifecta”: A surging payout that hauls the share price higher (a pattern I call the “Dividend Magnet”), with an extra “kick” as buybacks pile more upward pressure on the stock.
Let me show you this sweet setup in action, with two stocks boasting big shareholder yields that definitely get our attention.
The first is a grocer the crowd has left for dead, down 24% from its 2026 high while its payout keeps climbing. The second is an “old-school” industrial name that quietly shovels dividends and buybacks out the door in equal measure.
Kroger’s 10.3% Shareholder Yield Is Stuck at the Back of the Shelf
Most investors look at the 2.7% current yield on Kroger (KR) shares and leave them on the shelf. That’s a shame, because the grocer has a history of shareholder-friendliness.
That’s pulled the stock higher as investors bought every hike—until they turned overly sour on the stock a few months ago after Q1 earnings missed by a penny (revenue actually topped expectations) and same-store sales growth slowed.
Management also hiked the payout 11% a week after the earnings report. The payout has now grown for 20 straight years, at a compounded annualized rate of 13%.
What’s the crowd discounting? New CEO Greg Foran, who joined the company in February after leading Walmart US for six years, racking up 20 straight quarters of same-store sales gains in that span. He’s focused on turning around that sluggish metric for Kroger, which has some stores that, I think you’ll agree, look a bit tired these days.
Greg says about 60% of Kroger’s stores need to up their game to compete with the rest. Some see a lot of work there—we see a lot of growth potential.
Foran’s growth focus gives us a nice springboard for the share price to bounce back—especially when you consider management’s long history of buying back stock. Check this out:
KR’s Share Count Drops, Boosting Its Dividend Magnet
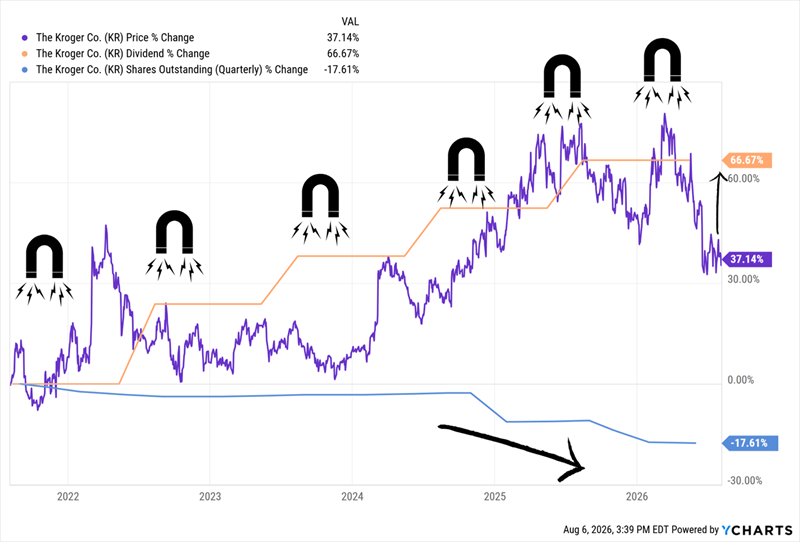
As you can see, Kroger’s stock was marching higher, along with the dividend, until it fell off the pace after Q1 earnings. That’s set up a nice gap to buy in and wait for the stock to snap back to the dividend growth. The 17.6% drop in the share count in the last five years only loads the spring further.
Which nicely sets up our shareholder yield calculation. To get it, we add the amount management has spent on dividends in its latest fiscal year ($889 million) and buybacks (a whopping $2.73 billion).
When we take the total ($3.62 billion) and divide it by the firm’s $35.1-billion market cap, we get a whopping 10.3% shareholder yield.
There is one caveat I do need to throw in here: The company authorized $2 billion in buybacks at the end of last year, down from its previous authorization of $7.5 billion. As a result, Kroger’s shareholder yield will likely be down some when we look back at this time next year.
But even so, that figure will almost certainly be much higher than the current 2.7% yield (on the dividend alone). And, again, for the best reason: Cash being used to boost same-store sales, the lifeblood of the company.
That leaves us with a tasty recipe (sorry, couldn’t help it!) for more payout and share-price growth as buybacks cut the number of shares outstanding, the dividend (which accounts for a mere 30% of free cash flow) marches higher, and Foran gets to work.
That’s a tidy setup for long-term share price—and dividend—growth. And it nicely sets up our next shareholder-yield play, whose high shareholder yield is built on a gusher of free cash flow that management isn’t getting enough credit for.
Illinois Tool Works’ 2.2% Yield Flips to 4.3%, Then “Stair Steps” to 5.4%+
Wall Street hates Illinois Tool Works (ITW) because the company doesn’t offer a “clean” story the way a Microsoft (MSFT) or Amazon.com (AMZN) does. It’s an old-school conglomerate with its hands in many different businesses, many of which have little overlap.
I’m talking everything from fasteners and plastic car parts to commercial kitchen equipment, welding materials and gear for testing electronics. But we’re fine with that because ITW is a cash cow: In its just-reported second-quarter results, free cash flow leaped 41%, to $630 million.
What’s more, revenue jumped 6.1%, and EPS popped 10%, with guidance hiked further for all of 2026. No wonder ITW’s divvie does nothing but stair-step higher. And note the clear-as-day Dividend Magnet at work here:
ITW’s Share Price Is Bolted to Its Payout
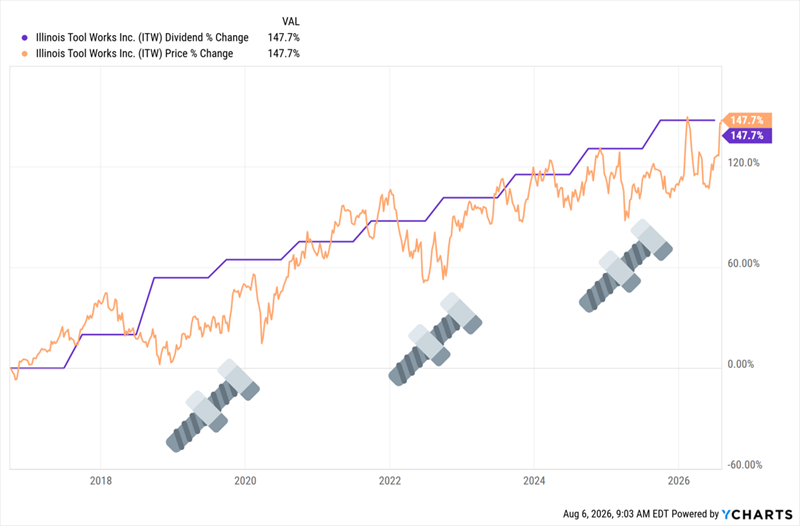
The stock’s current yield is around 2.2%. But (of course!) this number masks the effect of dividend growth and buybacks.
Before we do a full shareholder yield calculation on ITW, let’s pause for a moment and note just how much a fast-growing dividend like this magnifies the yield on money invested over time.
That’s another one of my favorite yields: yield on cost—and in the case of ITW, it’s substantial: Anyone who bought 10 years ago is getting around 2.5X the stock’s current yield out of their upfront investment: a stout 5.4%.
Now let’s bring it back to today and talk shareholder yield. It’s particularly important here because ITW spends nearly as much on buybacks (around $1.875 billion in the last four quarters) as it does on dividends (roughly $1.8 billion). Add those two together ($3.675 billion) and divide by ITW’s $85.2-billion market cap and you get a shareholder yield of 4.3%.
That’s about 2X today’s 2.2% current yield and leaves us with a very nice “dividend ladder”: We start with that 2.2% current yield (which is around 2X the typical S&P 500 yield). Then buybacks take us one rung higher, to a shareholder yield of 4.3%. Then, over time, our yield on cost takes us to the top rung: a tidy 5.4% yield on cost.
Sweet! Best part is, all we need to do is buy now, then sit back as this “old-school” conglomerate’s quietly surging cash flow pushes up our favorite yield metrics even more.
5 Soaring Dividends We’re Buying Now (as Other Investors Starve for Yield)
Look, I know it’s not easy to find the healthy yields we need to fund our retirements these days.
But I’ve just showed you how shareholder yield—not current yield—opens up a whole new field where we can hunt for large, and growing, income streams, and big gains too.
Smart, next-level thinking like this is the key to building our net worth, and our dividends, in a sky-high market like this one. And I’m not going to leave you with just two tickers to consider.
That’s because my Dividend Magnet strategy has uncovered more—5 more, to be precise—stocks whose payouts are not only growing but accelerating, boosting their stocks’ shareholder yield as they do, and pulling their share prices higher, as they do.
I’m ready to show them to you now—and give you a free Special Report revealing their names and tickers. Click here to get more details—including a full breakdown of my Dividend Magnet strategy and your own copy of that exclusive report—now.