At my CEF Insider service, we’ve long seen high-yield bonds as a critical part of our portfolio. And I’ve got a bond fund for you today that:
- Has crushed stocks in the last five years (which is pretty well unheard of for a fund holding corporate bonds).
- Generates a high, stable yield (I’m talking 7.5% payouts here, with the odd special dividend thrown in).
- Is cheap, with a discount to net asset value (NAV, or the value of its underlying portfolio) of 8.8%. And I see that discount resuming its march toward par, putting upside pressure on the fund’s price as it does.
Another reason why we love high-yield bonds is that they’re overlooked (nay, even hated) now, in part because higher interest rates have weighed on them (and higher rates push bond prices down).
The upside? The resulting lower bond prices push up bond yields. And now, with rates and yields remaining stubbornly high, is a good time to buy, then hold as rates move lower in the long run, driving up bond prices.
That, in turn, will make high-yield bonds bought today more valuable, as new ones are issued at lower rates.
And there’s another reason why bonds are being ignored right now: overdone fear of defaults.
Here’s the thing that doesn’t seem to be sticking in investors’ minds, though: Over the last 25 years, corporate-bond default rates have hovered around 2.5%. In other words, if we own a portfolio of, say, 200 bonds, just five of them will default. And even in those cases, investors recover a percentage of their investment—they rarely lose it all.
And if we’re earning, say, a 7.2% yield on all of the 200 bonds in that portfolio, even after the five defaults, the effect on our overall income stream would be minor. This matters for a couple of reasons.
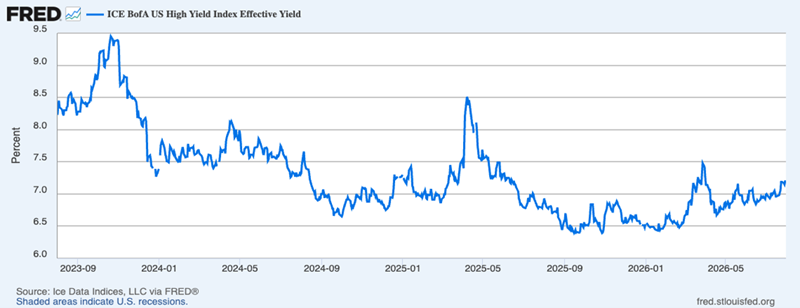
The first is that, if we buy into these high-yield bonds, we can expect a 7.2% income stream off the bat. That’s the average effective yield of high-yield bonds at the moment, and that yield has been going up in 2026 as investors grow more concerned about the direction of interest rates and, to a lesser degree, over default rates. (Remember that falling bond prices mean higher bond yields.)
Thing is, the default rate is not rising.
Which brings me back to the closed-end fund (CEF) I touched on off the top: the PIMCO Dynamic Income Strategy Fund (PDX), a holding in our CEF Insider portfolio. PDX, as mentioned, has done something shocking for a bond fund: It’s delivered a total return that’s beaten that of the S&P 500 over the last five years.
PDX Beats Stocks
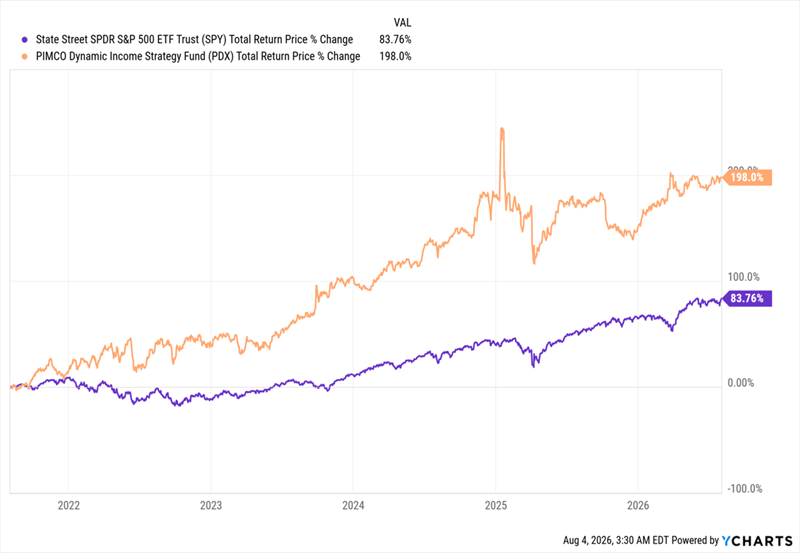
As you can see above, over that time, the main S&P 500 index fund (in purple) has posted an 83.8% total return, or an impressive 12.9% annualized. Meantime, PDX (in orange) has delivered 24.4% per year on an annualized basis.
To be sure, that’s in part due to leverage. But PIMCO keeps the amount of total effective leverage modest, at around 22% of the portfolio. So it provides a growth push without adding unacceptable levels of risk. Then there’s the income stream:
A Reliable 7.5% Dividend With a Special-Payout “Kicker”
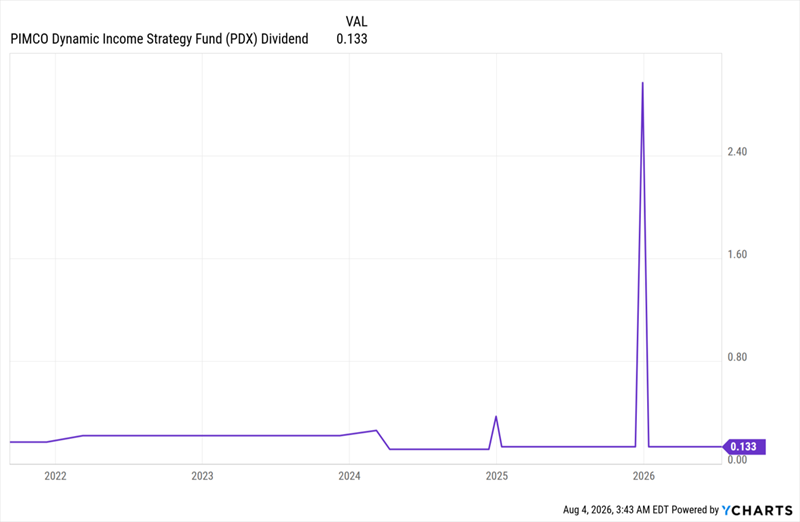
To be clear, management did cut the payout in 2024, but since then the fund has maintained payouts and made up for much of the cut through two special dividends.
How can PDX do this? One reason is that discount to NAV I mentioned a second ago. When we look at the fund’s yield as calculated by its discounted market price, we see that it pays 7.5%. That’s the yield we get.
But when we divide the annualized regular payout by the per-share NAV, we get a substantially lower number: 6.8%. That’s what management needs to get from its portfolio to maintain its payout.
And since this is below the 7.2% current yield of high-yield bonds generally, we should expect PDX’s payout to at least hold steady.
Now let’s talk upside.
PDX’s Discount Looks Set to Narrow Further
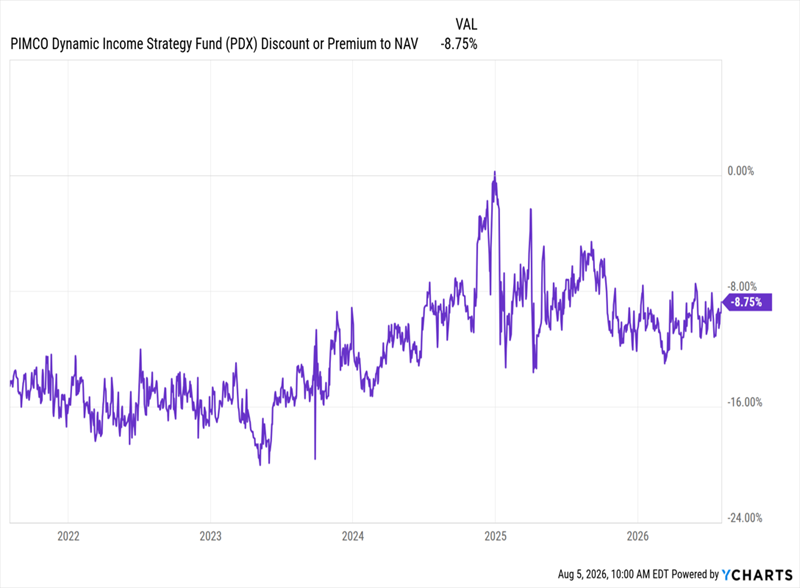
PDX’s discount remained tightly rangebound around 16% in the early years of this decade, but in 2024, it began to narrow and settled in a new range around 9%, where it sits now. That’s thanks in large part to the fund’s accelerating gains from its portfolio, which, as mentioned, is diversified across 390 bonds.
This diversification helps cushion PDX’s downside in a falling market, as does the deep discount. That same discount would also put upside pressure under the price when bond demand rises, as I expect to happen—especially when rates move lower.
I should also mention that a discount this wide is rare for a fund from PIMCO, whose funds tend to trade at premiums, due to the firm’s strong reputation in the CEF space. That’s another factor likely to push this discount toward par, as investors look to invest with PIMCO and are naturally drawn to this fund’s unusual discount.
Inefficiencies like this rarely last, so I expect PDX’s discount to resume its march toward par soon. Until then, we continue to see the fund as a buy for its well-covered dividend and upside potential.
4 More Huge Dividends (9.9% on Average) The Crowd Has Left Behind
PDX is the kind of fund we love to find, with a big payout and plenty of tailwinds behind it—but the crowd is still illogically ignoring it.
The result? A rare discount setting us up for price gains later, while we collect a high, stable payout now.
I’ve got 4 more CEFs for you that are in the exact same spot: They come from across the economy, holding top blue-chip stocks, bonds, REITs, tech stocks and more. My latest analysis suggests 20%+ price gains are on the table in the next 12 months. And that’s in addition to these funds’ outsized 9.9% average dividends.
These are the kind of funds we can “set and forget”—happily collecting their steady double-digit income streams while we wait for those price gains to materialize.
Click here and I’ll tell you more about each of these 4 dynamic income funds and give you a free Special Report revealing their names and tickers.